RuPay UPI Credit Cards Explained: Should You Link Your Credit Card to UPI?
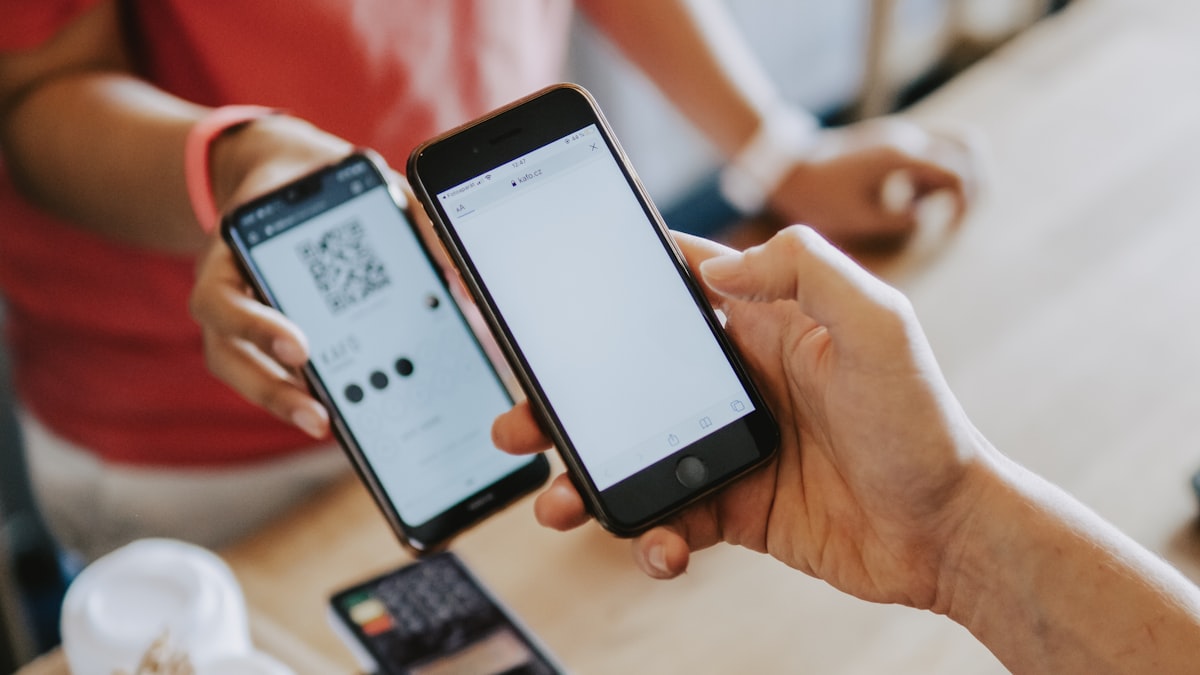
UPI-linked credit card transactions now make up a large and fast-growing share of all Indian credit card spending, most of it through RuPay credit cards linked directly to a UPI ID. If you’ve seen the option to “link credit card” inside your UPI app and wondered whether it’s worth doing, here’s what actually changes.
How it works
Instead of linking only your bank account to UPI (the default setup), you can additionally link an eligible RuPay credit card to your UPI ID. Once linked, you can pay any UPI QR code using your credit card’s credit line instead of debiting your bank account directly. No physical card, no POS machine, just scan and pay like you normally would with UPI.
What you actually gain
- Credit-line spending everywhere UPI works: including small shops, street vendors, and anywhere else that only has a UPI QR code, not a card machine
- Rewards on spends that previously earned nothing: small daily UPI payments (chai, groceries, auto rides) that used to come straight out of your bank account can now earn whatever rewards your credit card offers
- No extra merchant fees on small transactions: payments under ₹2,000 at small offline merchants typically don’t attract merchant discount rate (MDR) charges passed on to you
- Same security as regular UPI: authenticated with your UPI PIN, with tokenization replacing your actual card number
What it does NOT let you do
- No person-to-person payments: you can pay merchants via UPI QR, but you cannot send money to friends or family using a linked credit card the way you can from a bank account
- No cash withdrawals: obviously, since this is credit, not your own money
- Only works with RuPay cards specifically: Visa/Mastercard credit cards aren’t part of this UPI-linking system in India; if your primary card is Visa or Mastercard, this feature isn’t available to you at all
Is it worth doing?
Worth it if:
- You already have a RuPay credit card sitting mostly unused because RuPay has historically had lower acceptance than Visa/Mastercard for card-present transactions. UPI linking gives that card a genuinely useful new use case
- You want your everyday small UPI spends to start earning card rewards instead of just leaving your bank account with nothing in return
Not worth restructuring your setup for if:
- Your primary card is Visa/Mastercard: you’d need to actually apply for and get approved for a separate RuPay card just to use this, which is a bigger commitment than the convenience justifies for most people
- You’re disciplined about paying your card in full: the benefit here is reward-earning and convenience, not savings, so don’t treat “spending via credit instead of debit” as free money if it changes your spending behavior
The one habit risk worth naming
Routing everyday small purchases through a credit line instead of your bank balance can make it easier to lose track of how much you’re actually spending day-to-day, since the money doesn’t visibly leave an account balance in the moment. If you link a credit card to UPI, it’s worth checking your card statement more often than “once a month when it’s due”, the same discipline we recommend for auditing UPI AutoPay mandates applies here too.
Whatever you spend through a UPI-linked credit card still counts toward your total monthly obligations. Track it alongside everything else in the SubsCut calculator rather than treating it as separate from your “real” spending.
FAQ
Can I link a Visa or Mastercard credit card to UPI? No, this feature is currently RuPay-only in India. Visa and Mastercard credit cards aren’t part of the UPI-linking system.
Can I send money to friends using a UPI-linked credit card? No, only merchant (P2M) QR payments are supported. Person-to-person transfers aren’t allowed from a linked credit card.
Related posts
Singapore Itinerary Planning: Where Self-Planning Actually Saves Money
A 5-day Singapore family itinerary showing where self-planning beats a package tour: combo tickets, MRT vs cabs, hawker food, and tourist passes.
Jio vs Airtel vs Vi: Are You Paying for Netflix or Prime Twice Through Your Recharge?
Jio, Airtel, and Vi postpaid plans now bundle Netflix, Prime, and JioHotstar. Check if your recharge already covers what you pay for separately.
Diaper Subscriptions in India: Do They Actually Save Money?
Whether subscribing to diapers on Amazon or other platforms actually saves money in India, and how much the discount is really worth over a year.