Dubai Real Estate for Indian Investors: The Complete 2026 Guide
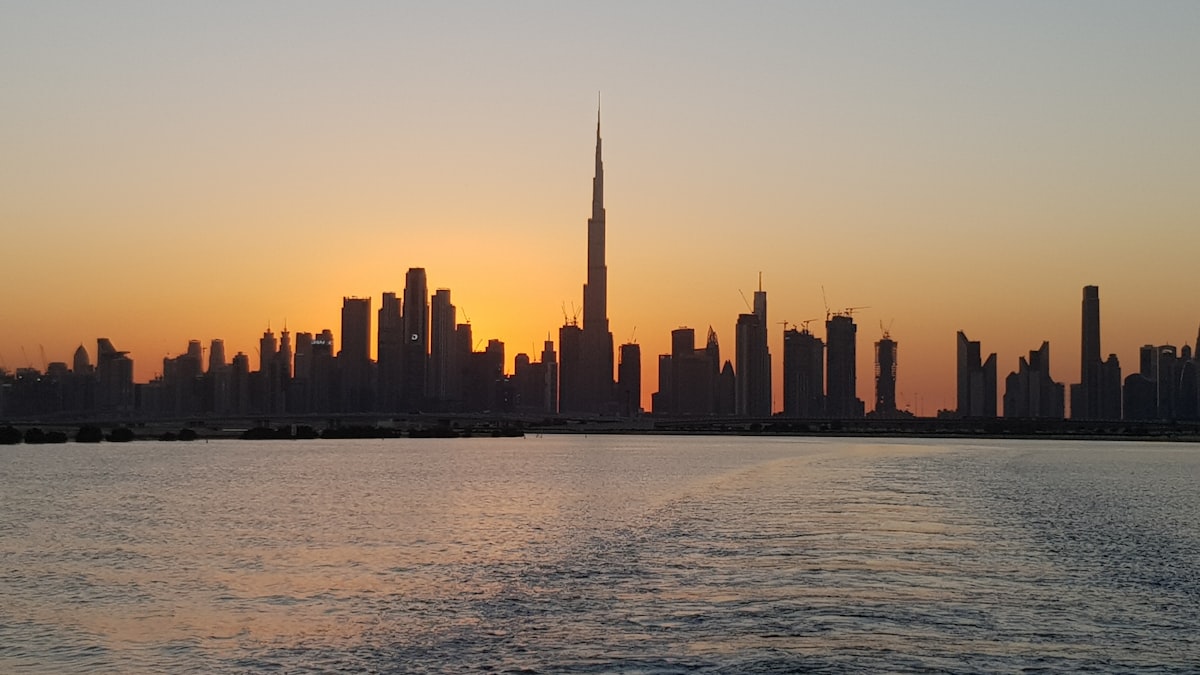
Dubai has quietly become one of the go-to overseas property markets for Indian investors. No property tax, no capital gains tax, and a currency that’s held close to its dollar peg for decades. It’s also a market that’s easy to get wrong in small, expensive ways, because freehold zone rules, remittance limits, and fee structures don’t work the same way property buying does in India. This guide covers the actual starting points.
Can you actually buy property in Dubai as an Indian?
Yes, with one condition. Non-UAE nationals can only buy in DLD-designated freehold zones, which are areas the Dubai government has specifically opened to foreign ownership. That still covers most of what Indian investors are looking at: Jumeirah Village Circle (JVC), Business Bay, Dubai Marina, Downtown Dubai, Dubai Hills Estate, Palm Jumeirah, and a long list of others. Outside these zones, foreign ownership isn’t generally permitted, so it’s worth confirming a project’s freehold status before you get attached to it.
Resident Indian vs NRI: the funding rules aren’t the same
This distinction matters more than almost anything else in the process.
Resident Indians fund the purchase by remitting money out of India, and that puts them under RBI’s Liberalised Remittance Scheme (LRS), capped at USD 250,000 per person per financial year. That ceiling isn’t specific to this one purchase either; it covers every foreign remittance you make in that year.
NRIs and OCIs usually fund from an NRE or NRO account, or from income already sitting abroad. LRS only applies to money leaving India, so funds that never originated there aren’t capped by it.
If you’re a Resident Indian and the property runs past roughly ₹2 crore (about USD 250,000), a single financial year’s LRS allowance won’t cover it on its own. That rules out certain price points unless you spread payments across financial years or bring in an NRI or OCI co-investor.
The fee stack most guides don’t mention
The listing price is never the full cost. Here’s what typically gets added on:
- DLD transfer fee: 4% of the property price
- Trustee or admin fee: a flat charge per transaction
- Agency commission: around 2% on resale purchases, usually nil on new off-plan units bought directly from a developer
- Mortgage registration fee: roughly 0.25% of the loan amount plus a flat charge, if you’re financing
Add it up and these fees typically run 6-7% on top of the headline price. On a ₹3.5 crore (AED 1,500,000) property, that’s an extra ₹20-25 lakh that a lot of first-time buyers don’t budget for until it’s already due.
Off-plan or ready: two different risk profiles
Ready properties are paid in full, or via mortgage, at transfer. They rent out immediately and carry no construction risk. Off-plan properties are bought through a payment plan spread across the construction period, often 20-30% at booking with the rest tied to construction milestones. The entry cost is lower, but the payoff depends heavily on the specific developer’s delivery track record, and that varies a lot even within the same brand.
Golden Visa: a second reason many Indians buy
Property worth AED 2,000,000 or more (around ₹4.7 crore) qualifies for the UAE’s 10-year Golden Visa. For a fair number of investors, the residency matters just as much as the return on the investment itself. We go into this separately in our Golden Visa guide.
Where to actually start
Don’t start by picking a community or developer. Start with your own budget, your goal (income, appreciation, or residency), and how much risk you’re comfortable carrying, and let those numbers point you toward a strategy. That’s the reasoning behind the Dubai Real Estate Strategy Portal: enter your budget and goals, and it matches you to a strategy, shortlists communities, and models the full cost stack including fees, yield, and off-plan payment schedule, in both AED and INR.
What to read next
- The real cost of buying Dubai property as an Indian: LRS, TCS, and the fee stack in full detail
- Off-plan vs ready property in Dubai
- NRI vs Resident Indian: how the rules differ
Related posts
Singapore Itinerary Planning: Where Self-Planning Actually Saves Money
A 5-day Singapore family itinerary showing where self-planning beats a package tour: combo tickets, MRT vs cabs, hawker food, and tourist passes.
Jio vs Airtel vs Vi: Are You Paying for Netflix or Prime Twice Through Your Recharge?
Jio, Airtel, and Vi postpaid plans now bundle Netflix, Prime, and JioHotstar. Check if your recharge already covers what you pay for separately.
Diaper Subscriptions in India: Do They Actually Save Money?
Whether subscribing to diapers on Amazon or other platforms actually saves money in India, and how much the discount is really worth over a year.